In 1981 the inaugural MTV music video was Video Killed the Radio Star; Today social media videos are similarly changing podcast economics
Then and now, it was about media economics. History has shown us how radio, a favorite medium of mine since I was a kid in a remote rural town, lost much of its ad dominance to television, and then further to cable TV.
Then came podcasts. To me they were a revelation! They were radio, but with topics scaled across what felt like an infinitely long tail — far more variety and specificity than broadcast or cable bandwidths could ever deliver.
And, Bonus! They were on demand, so I could listen on my terms!
Back in its infancy, podcasting was like a specific type of audio: college radio. In that there was zero money in it.
I mused on this very site, 20 years ago, how podcasts might change that. I even predicted in Monetizing podcasts that we could have ad buys and sponsorships as the drivers of its business model. Of course what I couldn’t predict back in 2006 was socially-distributed videos and clips — which have knocked out of our ears the voices of, to name three, Dana Stevens, Stephen Metcalf, and Mike Pesca.
Below you’ll learn from Mike why his voice, and possibly others, are no longer in our podcast feeds. You’ll also get a prediction for how video podcasts may themselves be facing a pivot, postulated by Ryan Broderick, the man behind the excellent Garbage Day newsletter.
Podcast promotional clips eat their masters
July of this year was not a happy time for me in terms of my media diet. First, Slate Culture Gabfest shut down after 18 years. And after 16 years, Mike Pesca’s The Gist met the same fate. Although I haven’t learned a reason for why the former podcast folded, Pesca was forthcoming about his, in a conversation about current podcast economics. The TL;DR in one word: Algorithms:
The co-host of Scott Galloway’s Prof G podcast, [Ed Elson], put out a social media clip, saying “Our clips are not only much more seen than the show. They’ve essentially become the show, when people think about who’s Scott Galloway and me, the sidekick. They only think about the clips on social media.”
So [the business model] has become inverted. Rather than having promotional materials for the show, the show becomes in service of these promotional materials. It is solely a vehicle to cut social media clips. [Ed was saying the clips were also] a major if not main way that the show made money: The promotional material about the show. And … if I started to do these social media clips, which I tried, and if somehow I got good at it and I was making a ton of money at it, I might say all right, I’ll lean into that. But that was never the case.
One bright spot for me personally was that before The Gist shut down, I got my question answered on a long-standing segment of the show, called Is That Bullsh*t? You can listen to the 14-minute excerpt below:
Is This Current Pivot To Video Finally Ending?
That was a subheading in a recent Garbage Day newsletter. Ryan Broderick gives his reasoning for why he thinks the answer is Yes:
YouTube has drastically changed what their front-facing metrics track — but not what they pay for you! Basically, opening a YouTube video now counts as a view, even though they’re still only paying you for “engaged views.”
MS Now will soon be airing Crooked Media “podcasts,” which are really just talk shows. YouTube channels are simulcasting on Netflix.
And I’m hearing from a lot of short-form creators lately that that entire realm is basically over if you want to make any real money.
“As for what’s next, my prediction is a complete hollowing out of the video middle class, as it were. Professionally produced studio shows and random people talking into their phones and basically nothing in between.”
Time will tell. If it does, maybe on-demand audio, the “theater of the mind,” will experience an economic resurgence.
In her most recent special, stand-up comic Isabel Hagen talked about hating what she calls nonconsensual magic tricks. While a clerk was giving her change, he pulled a quarter out of her ear. She explained, “You gotta ask first, ‘Do ya wanna see a magic trick?’ Otherwise, it’s just deceit.” I worked in technology during the bursting of the dot-com bubble in the year 2000, and I can speak with firsthand knowledge about the similarities of that bubble and what we’re seeing today. But so what? It’s a claim any technologist might make who is old enough to remember the original Charlie’s Angels.
There’s something more unusual that qualifies me to play Cassandra here. An earlier career had trained me in the psychology of deceit. I learned a mental Jiu Jitsu that can also be used to sustain bubbles.
That first career started when I was 12, the year I was “discovered” while performing magic tricks in the basement of my hometown’s public library. I had been studying magic and building a rudimentary act for a year or so. This was my first show to kids I did not know. It went well, and although I couldn’t articulate it at the time, what most drew me to magic was the psychological principles that make it possible.
Here’s a simple example: I learned early that adults were much easier to fool than children. And paradoxically, the more intelligent an adult was, the easier still. I’ll explain why later.
When I say I was discovered, I’m not kidding. My hometown children’s librarian happened to be a dear friend of a touring, highly respected magician, one who was in town between gigs. He was standing in the back and afterward pulled me aside to ask how serious I was about magic. Dumb question! It was an obsession. That was the beginning of a decade-long apprenticeship, and my first career: Fooling people for fun (theirs and mine) and profit.
AI itself is no illusion
Let me be clear: I think AI is miraculous. Especially for marketing technologists like me. Just as the internet and the world-wide-web have proven to be of sustained, world-changing value, AI is the same. The difference? AI is more consequential than the internet by at least one order of magnitude, and probably several.
I love AI. But I’m terrified by the warning signs I’m seeing, and feeling twinges of a quarter-century-old PTSD.
Doctorow explains that growth stocks are valued quite differently than mature ones. It’s this difference that has triggered this particular technology bubble.
Historically, Meta, Amazon and Google (Alphabet) stocks have had much higher values compared to mature stocks like Johnson and Johnson, Walmart, and Procter and Gamble. The higher values compared to present earnings reflect the fact that investors are betting that there are still many large and lucrative bites to be taken out of growth stock apples … before nature takes its course and the companies mature, at which point earnings still grow but at a lower, steadier rate.
Companies, like humans, yearn to appear younger
Meta, Amazon and Google have really enjoyed being growth stocks. As Doctorow explains, “When a company has a solid growth stock, other people want that stock. The company can use its stock to buy stuff, like other companies. Key personnel can be hired at whopping compensation rates, with the majority of that compensation coming in stock.”
The problem is these three stocks and many others are getting a little long in the tooth.
They’ve recently sought something to help them resume rapid revenue growth. That’s why, for maturing stocks, going all-in on AI was a no-brainer. If their investments in AI work out, everyone wins. Including you and your growing retirement stock portfolio.
You may have noticed, however, that things aren’t going swimmingly.
Here’s one example: To quote Aswath Damodaran, of Stern School of Business at NYU and a guest on an episode of Prof G Markets podcast, called Big Tech Has No Idea How AI Pays Off, “When I was looking at the prospectus of SpaceX [the home of xAI and Grok], I noticed that they were making more money by leasing out their data centers to others — in this case, Anthropic — than they were making from AI. I thought that was seriously at odds with their AI story. They were telling, in the prospectus, of this huge market, $28 trillion. [Now they reveal they are] making more money by selling into the AI architecture space.
“It’s very revealing. It tells me that you are not as confident as you claim to be … If you were really confident that there was going to be a huge market you wouldn’t want to lease the space out to potential competitors.”
From compute supply shortages to a demand crisis
Co-host Scott Galloway added it’s the same story from Meta. “Both Musk and Zuckerberg are trying to spin it as, ‘Look at the premium we’re getting for the infrastructure we’ve built!’ What I see in that is that the AI demand curve has been vastly overestimated. And now you have, essentially, hundreds of billions, if not trillions, of dollars in [capital investments], all going to only two sources of demand creation, OpenAI and Anthropic. It feels like we have all of a sudden pivoted from a supply crisis [because of a shortage of compute from data centers] to potentially a demand crisis.”
How downright bubblicious.
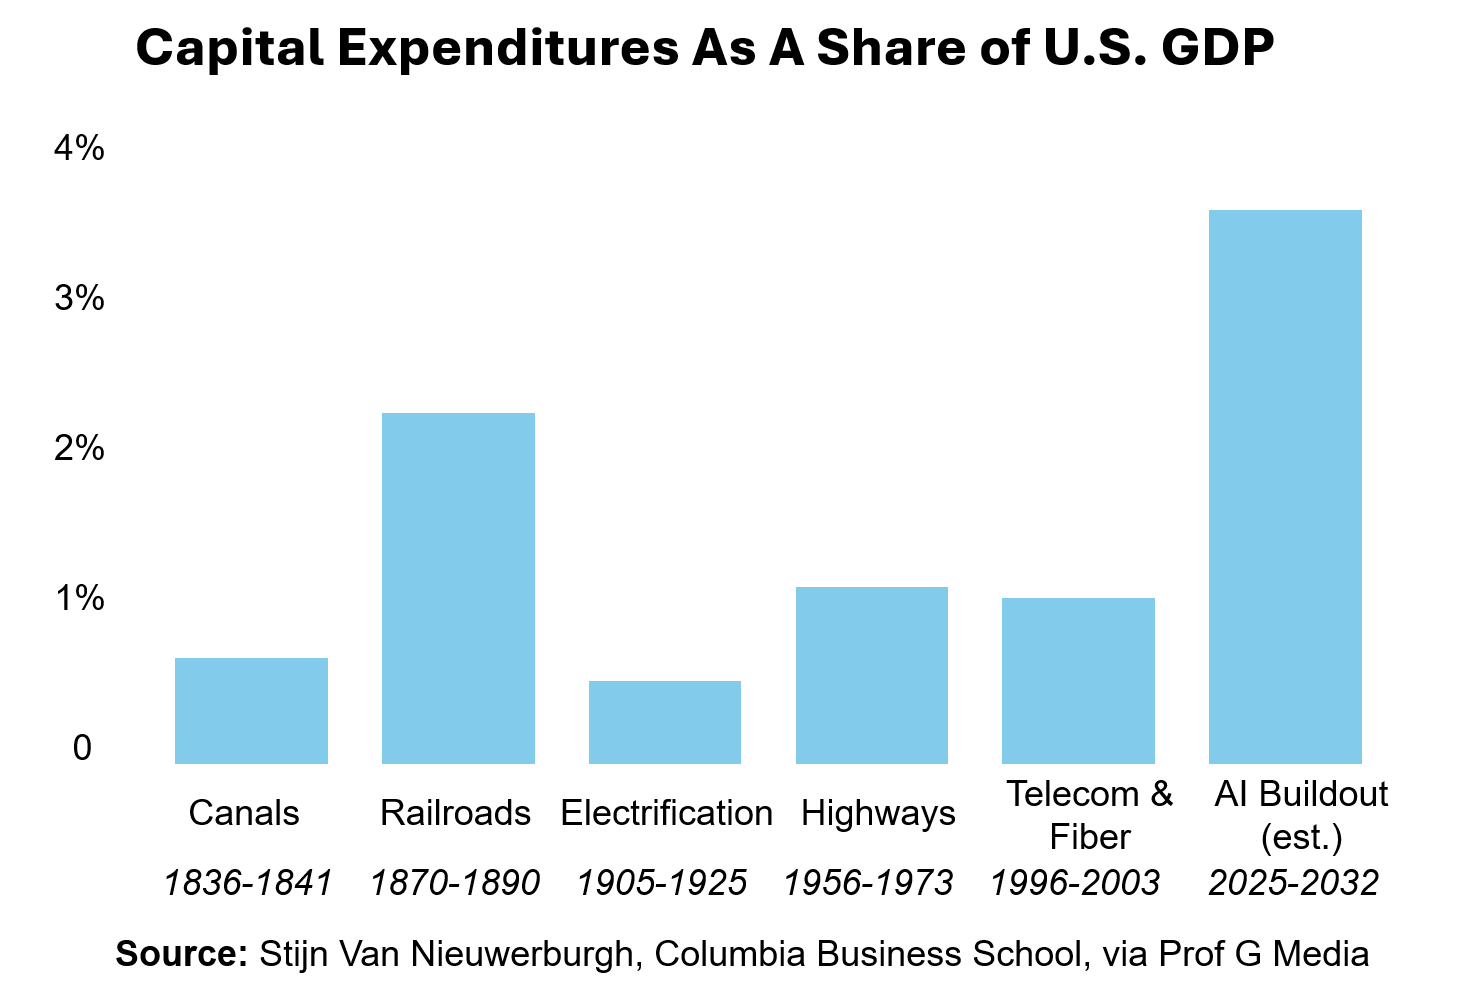
The chart below shows a uniquely high level of capital investments (capex). This money is in service of basically just two companies addressing all AI demand, OpenAI and Anthropic … which are, by the way, both hemorrhaging cash.
Look at the height of that far right bar in the chart, which compares the capex contributions to the U.S. gross domestic product (GDP) during various technology transformation spurts. Our country’s current annualized GDP is just 1.5 percent.
The takeaway: While these percentages should not be combined, it’s hard not to see that if there was no investment in AI infrastructure, we would likely be in a pretty nasty recession.
What about the AI job apocalypse?
It’s worth noting here that Professor Galloway believes, along with Doctorow and others, that the catastrophizing about an “AI job apocalypse” is actually, “fundraising and techno-narcissism.” What, you ask? Fundraising? Yes. It turns out when you wave under the noses of CEOs confident assurances that thousands of their employees can be replaced by AI, few can resist.
I’ve linked to the full YouTube recording of the podcast and I recommend you check it out. Damodaran and the hosts discuss other signals that reality isn’t living up to the AI hype. And when I say AI hype, I mean AI stock value hype.
Just as the dot-com surge a quarter century ago was not built on a lie, and spawned the very Metas, Amazons and Googles we’ve come to profit from as they’ve fattened our 401(k)s and investment portfolios, AI itself will change the world.
But AI-related stock values today appear to be mathematically untenable.
Two things you can do right now
Your savings — I’m not a financial advisor, and the strategy you take to protect your retirement savings to the greatest extent is something you should discuss with one. Keep in mind that if you are younger, you might just hold tight with your existing savings strategy. Why? It took only seven years for the S&P 500 to return to pre-bubble values.
Your career — Knowledge is power. If you want to learn more about the AI-enabled growth of reverse centaur jobs, this companion to Doctorow’s book is excellent. Also published this year, it’s by award-winning Financial Times journalist Sarah O’Connor. The title: We Are Not Machines: The Fight for the Future of Work.
Nothing up my sleeve! Four trickster secrets revealed
So how do you, if you’re in the business of growing already overvalued stocks, keep alive the illusion … the promise of future riches? The key word is illusion. Below I list methods I first learned when my voice was still changing.
Tactic #1: The Byzantine premium
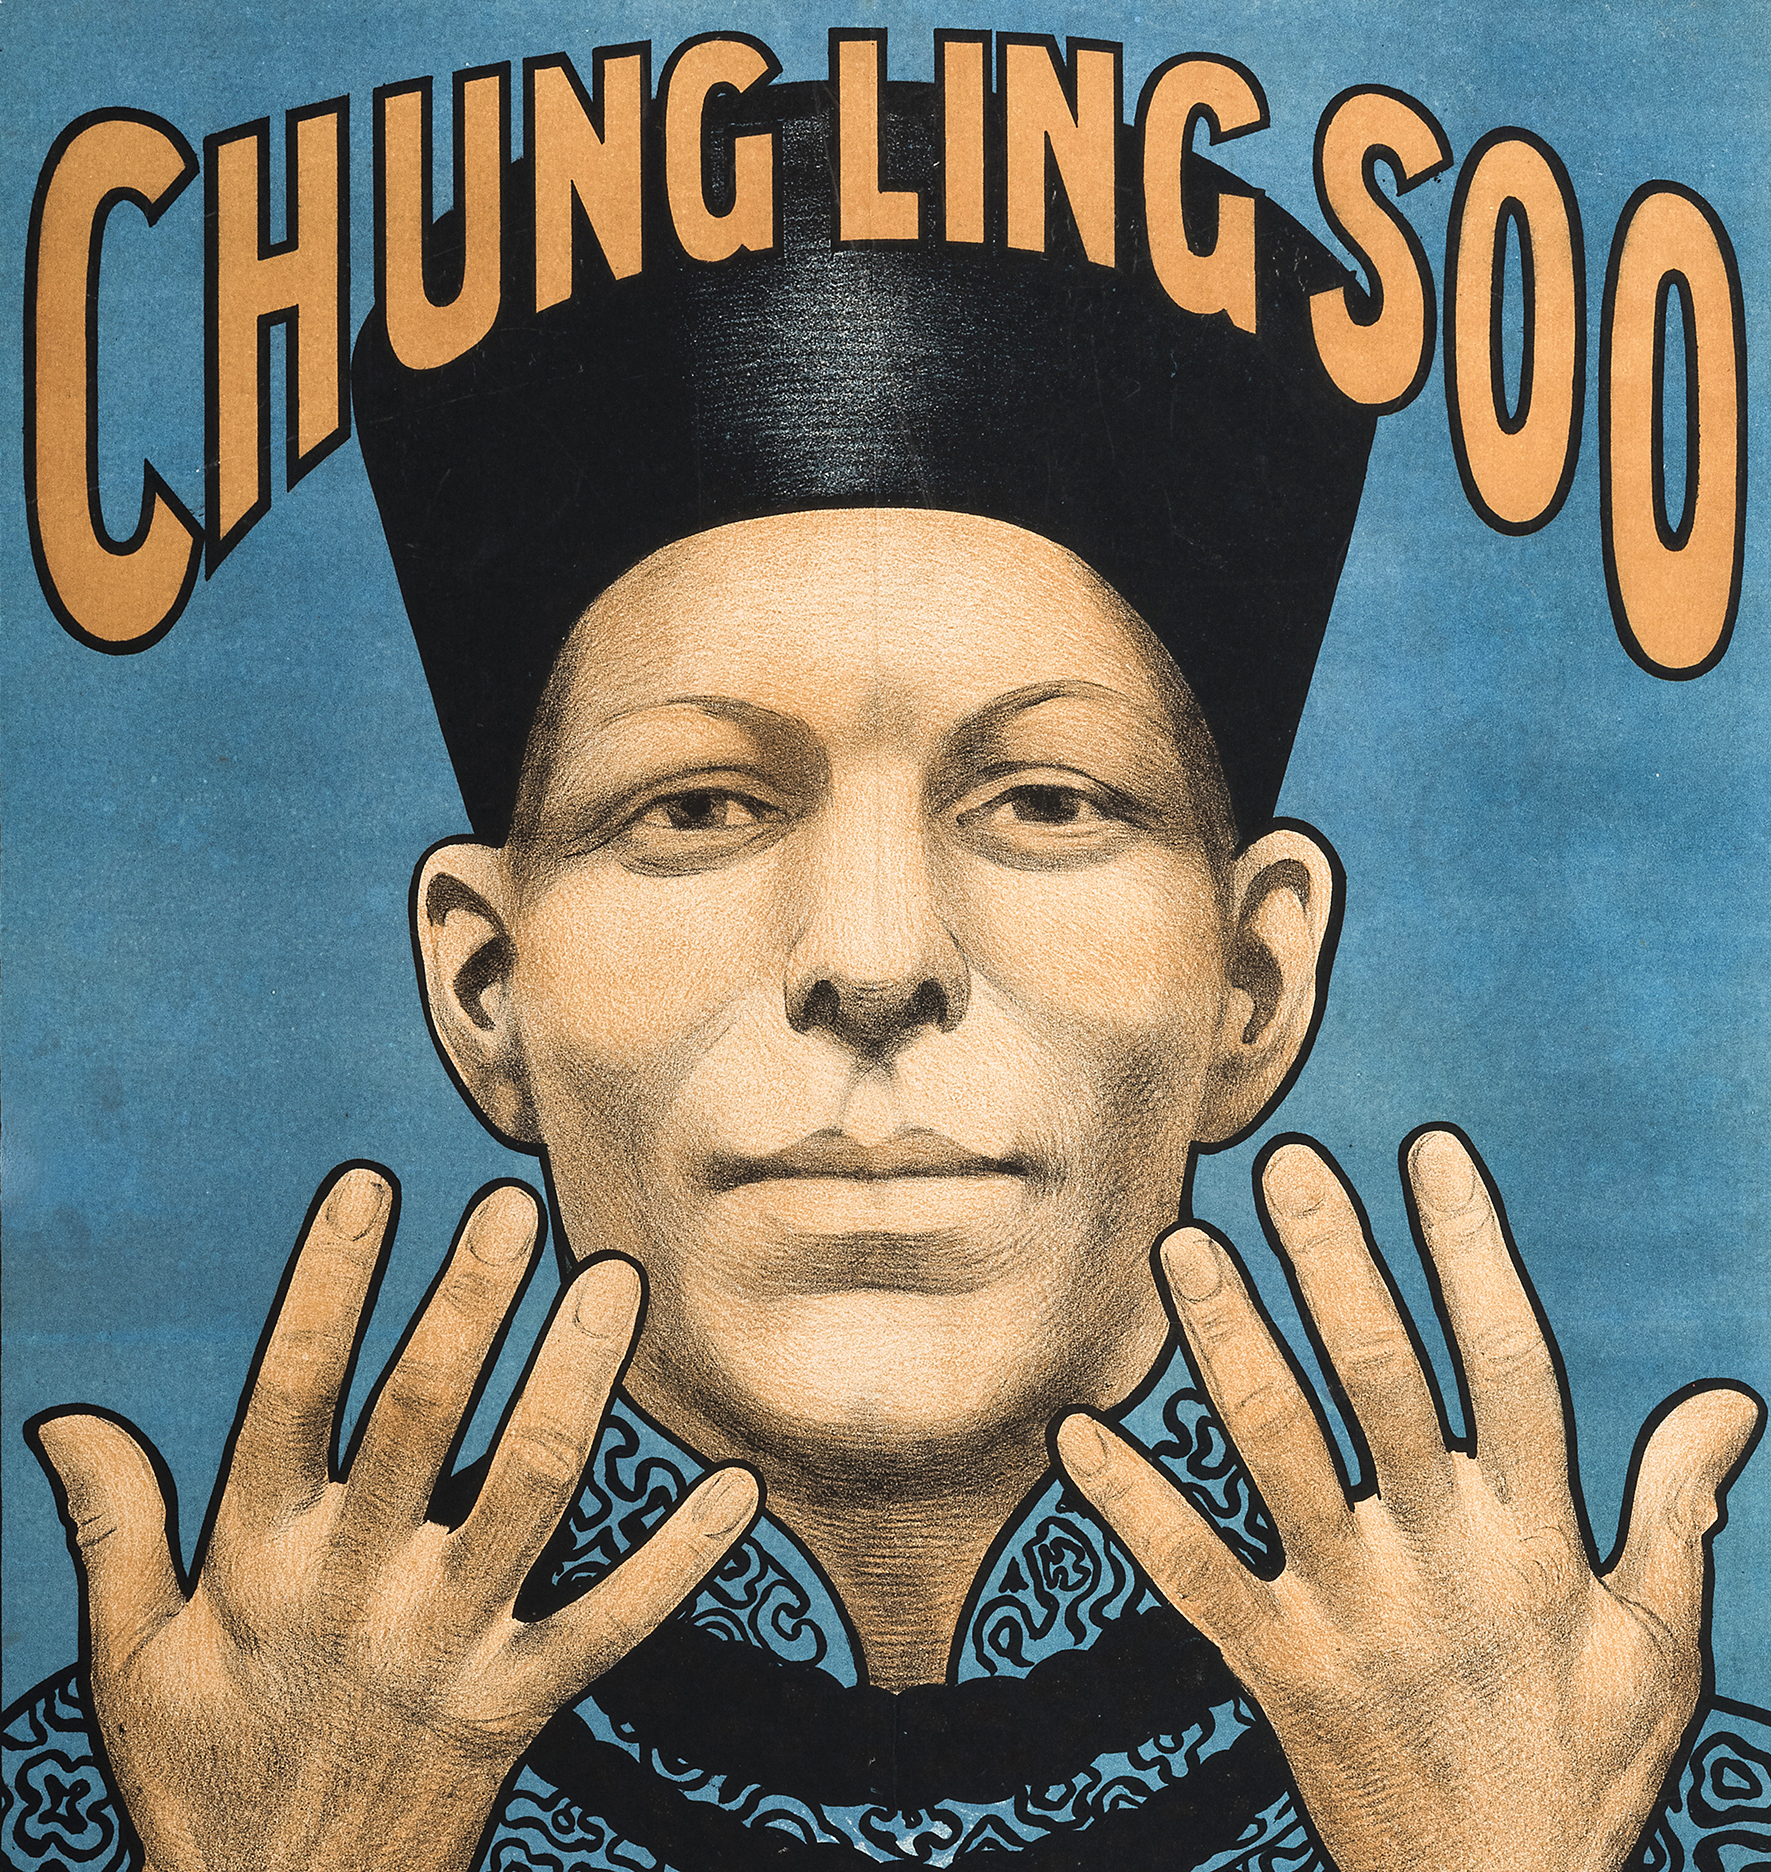
In my childhood studies I learned that around the turn of the last century, stage magicians would roll out complicated and exotically decorated props from “The Orient.” To Western audiences of the time, things from Asia were considered mysterious and prone to magical properties. One notable American magician, William Ellsworth Robinson, went so far as to perform in elaborate make-up, under the stage name of Chung Ling Soo. A portion of a poster promoting his show adorns this blog post.
He guarded this ruse of being Asian as tightly as if his career depended on it. It probably did. Appearing inscrutable made his tricks more convincing.
Fast-forward to today. Cory Doctorow explains, “Tech bubbles are surprisingly easy to generate, thanks to something economists call ‘the Byzantine premium.’ That’s the extra value that investors place on an asset that they don’t understand.” That is as true today as it was in the year 2000.
He goes on, “They assume that any pile of shit of sufficient size must have a pony under it somewhere.”
Tactic #2: Pleasant surprises deliver dopamine hits
The performances of comic Isabel Hagen and those of magicians have something in common: A series of delightful surprises. What we’re feeling when we experience them is literally visceral. It’s the release of dopamine, the pleasure hormone.
Now picture yourself in a boardroom, seeing a live demonstration of AI that a company wants to sell to your enterprise. Super impressive! Then imagine each of these same board members going home and playing with a chatbot.
As I described in this post on my personal blog, Reading and Writing in the Age of AI, “The intelligence we confer to the text coming out of chatbots is an illusion. … Like a magic show. At a Penn and Teller performance, the magic doesn’t occur onstage. The illusion takes place in our minds, as the duo crafts situations where our assumptions and biases fill in perceptual blind spots, and we consequently ‘see’ the impossible.”
The response from the board members, who have had their beachheads sufficiently softened by these repeated dopamine hits? “Get out our checkbook!”
Tactic #3: Cognitive biases can influence us and we don’t even realize it
I’ve spent the most recent part of my marketing technology career overseeing testing and personalization systems, specifically for selling to consumers. As I mention in this five-minute YouTube excerpt of a talk I gave in 2018, to an Adobe Summit audience in Las Vegas, hidden but measurable psychological quirks, such as confirmation bias and loss aversion, turbocharge those personalization tools. (And, incidentally, serve as fuel for magic tricks.)
Yet I warn my audience that the people operating personalization systems can be just as susceptible to biases as the consumers they sell to. They can fool themselves and not even realize it, ruining the results of their controlled randomized tests.
In a similar way, I am not saying that those in the AI Value Hype Industrial Complex are conscious of their biases toward AI as an Enterprise Money Printing Press. They may be true believers. What’s more, as Upton Sinclair famously wrote, “It is difficult to get a man to understand something when his salary depends upon his not understanding it.”
Tactic #4: Build hidden compartments
This isn’t so much a subtle psychological tactic as naked deception. But you cannot argue with success. There is nothing in stage magic more tried-and-true than hidden compartments. We’ve all seen exposés revealing that the assistant was hidden in that fancy box the whole time.
Now imagine the box is a corporate balance sheet, and the hidden assistant is a monster.
Major hyperscalers are building financial artifices, to the alarm of respected authorities like Ed Zitron. It’s true that many started by relying purely on debt they disclosed on their balance sheets. Yet today, as costs skyrocket, much of hyperscaler capital is externally financed, hiding considerable financial risk. A popular way is something called a special purpose vehicle (SPV).
To quote Zitron: “The problem with these SPV-based deals is that they allow companies to, at least on a balance sheet, hide the scale of their debts. … This is all legal, worrying, and yes, a little bit Enron.”
Similar to how collateralized debt obligations (CDOs), which caused the Great Recession of 2008, were eventually regulated, someday so will SPVs. Someday. But like CDOs, I’m convinced that regulation won’t happen until the damage to our world economy is done.
If you want to vanish an elephant, do it in front of a Mensa chapter
I promised to explain why highly intelligent adults are easier to fool than those with average IQs, and why both are easier to fool than children.
Younger brains are still being wired. That means they see the world much less predisposed to assumptions than you or me. On the other end of the spectrum, the most intelligent adults got that way by considering certain observations as settled law. They’re called heuristics: That glass salt shaker is full of salt, not painted to look that way. That single playing card is just that, not hiding another card flush against it.
Some of the greatest intellects in the world have convinced themselves that the law of gravity behind meteoric stock gains has been rescinded this time, ignoring history. It’s a truism that goes all the way back to the Dutch tulip bubble, in the 1630s.
They all fell victim to nonconsensual magic tricks.